Customer operations leaders are under pressure from almost every direction.
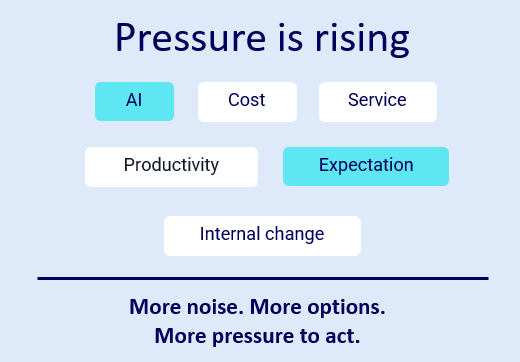
AI is now part of almost every conversation, while costs remain under scrutiny and customer expectations continue to rise. At the same time, organisations are being asked to improve productivity and service performance, manage internal change and adopt new technology, often without significantly increasing operational complexity or cost.
There is certainly no shortage of ideas or potential solutions in the market. The harder question for many organisations is deciding which of those options will actually address the underlying problem and deliver a meaningful, measurable outcome.
That is the picture emerging in our Q3 market overview: the market is active, but activity does not always translate into progress
The move from interest to pressure
AI has moved firmly into the customer operations conversation, but practical adoption remains uneven, with many organisations still working through how to translate the possibilities of the technology into specific operational improvements.
Organisations are being asked to modernise, reduce costs and improve service, often at the same time, yet many are still working through a more fundamental question: what is actually going to solve the problem?
For some, the answer may be technology. For others, it could be outsourcing, operational optimisation or consulting. In many cases, it may be a combination of several approaches, depending on the organisation’s existing capabilities, objectives and appetite for change.
The challenge is that these options are not always directly comparable, and choosing between them requires an understanding of not only what each solution can deliver, but also how it fits with the organisation’s commercial objectives, operating model and existing customer operation.
Customer operations leaders are therefore facing more noise, more options and more pressure to act, creating a growing need for a clearer way to move from a broad set of possibilities towards a decision that can actually be delivered.
The opportunity is not simply to add another option to the conversation. It is to help buyers turn that pressure into a clear, deliverable decision.
The biggest gap is decision confidence
Customer operations decisions now involve more stakeholders than ever, with commercial, operational, technology, risk, compliance and people agendas all having a role to play. While these stakeholders may share the same overall objective, their priorities and measures of success are not always aligned, making an already complex decision more difficult to navigate.
ROI is also being challenged harder, particularly as organisations look beyond the initial cost of a solution and consider its wider impact on service, productivity, customer experience, implementation and ongoing operational performance.
Where decisions could affect customer experience, brand reputation, compliance or operational performance, buyers are understandably cautious about making the wrong move.
There is another complication: some of the options being compared are not genuinely like-for-like.
A technology platform, an outsourced operating model, an internal optimisation programme and a consultancy engagement may all appear to address the same problem, but they solve it in very different ways and can require very different levels of investment, organisational change and operational commitment.
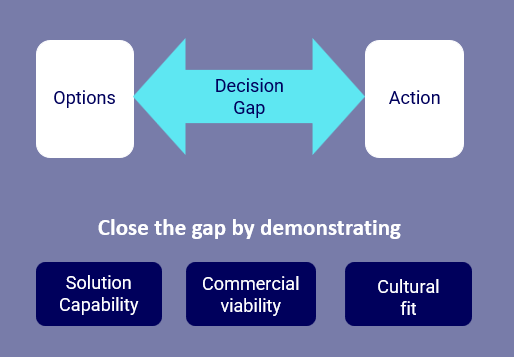
This creates what we would describe as a decision gap: there can be plenty of options on the table, but a lack of confidence about which option is actually right for the organisation, the operation and the outcome it is trying to achieve.
That changes the nature of the conversation.
The strongest conversations are not necessarily about providing more choice. They are about creating stronger decision confidence by helping organisations understand the problem, challenge the available options and establish which route is most capable of delivering the outcome they need.
From experimentation to execution
AI provides perhaps the clearest example of this shift.
Organisations are under pressure to demonstrate progress, but many are still working out where to start and, importantly, where AI can create genuine operational value rather than simply adding another layer of technology to an already complex environment.
There is no shortage of possible applications. In customer operations, some of the strongest opportunities we are seeing sit around areas such as:
- Agent assist
- Knowledge management
- Quality assurance
- Customer and operational insight
- Routing
- Forecasting
- Summarisation
- Root-cause analysis
These use cases can offer meaningful opportunities to improve how customer operations work, whether that means giving agents better information, improving the consistency of quality management, identifying patterns in customer interactions or helping organisations understand the underlying causes of operational issues.
But possibility is not the same as readiness.
Buyers are increasingly alert to the practical implications of introducing AI, including experience, compliance, accuracy, data quality, adoption and reputational risk. A use case that looks compelling in isolation still needs to work within the realities of the organisation’s data, systems, processes, people and governance environment.
This creates a growing gap between AI ambition and operational readiness, where organisations can see the potential of the technology but have not necessarily established the foundations required to deploy it effectively and responsibly.
The question is therefore changing.
It is moving away from:
“What can AI do?”
Towards:
“What should we trust AI to do?”
That is an important distinction because the value of AI in customer operations will not simply come from identifying everything that the technology is technically capable of doing. It will come from understanding where it can be applied safely, where human involvement remains important and where the resulting change can be measured against a meaningful operational or customer outcome.
Where AI creates value matters as much as what it can do
The next stage of the AI conversation is not simply about experimentation. It is about understanding where AI can be safely applied, how it changes the operating model and how its value can be demonstrated once it moves beyond the pilot stage.
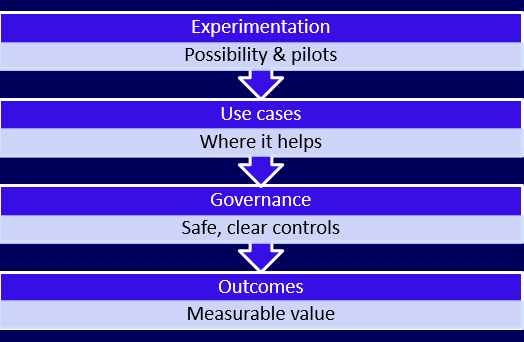
That means moving through several stages.
First comes experimentation and the recognition of what is possible, followed by pilots that allow organisations to test specific ideas in a controlled environment and understand whether they translate into meaningful operational improvements.
From there, organisations need to identify the use cases where AI genuinely helps, rather than applying it simply because the technology exists or because there is pressure to demonstrate that an organisation is doing something with AI.
Governance then becomes critical.
Clear controls, sensible guardrails and appropriate oversight are needed to make sure that experimentation can become something operationally useful and responsible, particularly where AI interacts directly with customers, influences decisions or handles sensitive operational information.
Ultimately, the conversation needs to reach outcomes.
What has changed? What value has been created? Has the customer experience improved? Has operational complexity reduced? Has productivity increased? Can the result be measured?
These questions move the conversation away from technology for technology’s sake and towards the practical role AI can play within a broader customer operations strategy.
The organisations that stand out will not necessarily be those making the biggest claims about AI. They will be those able to demonstrate clear use cases, credible evidence, sensible governance and measurable outcomes, while being able to explain how those outcomes connect to the wider objectives of the customer operation.
Closing the gap
This is where the wider customer operations market is heading.
The challenge is no longer simply finding a supplier, platform or technology that could potentially solve a problem. As the number of available options continues to grow, organisations increasingly need to understand the problem properly, evaluate the available routes and build enough confidence to move from decision to delivery.
That requires a different kind of conversation.
One that starts with the ask and considers what the organisation is actually trying to achieve, rather than starting with a particular technology, supplier or predefined solution.
One that considers the operational context, commercial viability, cultural fit and capability required, recognising that a solution can look attractive on paper but still be unsuitable if it does not fit the organisation or the people expected to deliver it.
And one that recognises that the right answer may be technology, outsourcing, optimisation, consulting or a combination of approaches, depending on the problem being addressed and the outcome required.
At Customer Contact Panel, this is how we approach customer operations.
As people, we understand the value of cultural, brand and relationship fit. As natural problem solvers, we start with the ask because the ask sets the strategy, whether that ultimately leads towards improving an existing operation, introducing new technology or finding the right outsourced partnership.
From there, the focus is on helping organisations shape their contact centre operations and find the right technology or outsourced partnerships to match their ambition.
The market will continue to produce more options, while AI will continue to create new possibilities and the pressure on customer operations will continue to grow.
But organisations need more than options. They need confidence in the decision, clarity on how to execute it and evidence that the chosen approach is creating measurable value.
The opportunity is to move from market noise to better decisions, and from better decisions to safe, measurable delivery.
Every ecommerce business wants the same thing. More customers. More orders. More revenue.
Yet many discover an uncomfortable truth: as demand grows, so does customer effort. Response times stretch, operational costs rise and teams become overwhelmed.
More people are recruited simply to keep pace. Processes become increasingly manual, and leadership spends more time solving operational problems than driving growth. The business continues to grow, but it becomes progressively harder and more expensive to serve every customer.
The question is no longer: Can we generate demand?
It becomes: Can our customer operation absorb growth without increasing cost, reducing trust or damaging the customer experience?
This is no longer a customer service challenge. It is a commercial one.
Growth Doesn’t Usually Fail Because of Marketing
Most ecommerce businesses are very good at generating demand. Marketing becomes more sophisticated. Customer acquisition improves. Conversion increases.
But operational capability often develops more slowly than commercial ambition.
Eventually, every additional £1 million of revenue can create:
- More customer contacts
- More manual intervention
- More exceptions
- More operational complexity
- Higher cost-to-serve
- Greater pressure on employees
Growth becomes increasingly dependent upon people working harder rather than the business working smarter.
The result? Margins begin to erode, customer confidence starts to weaken and employee frustration grows. Growth itself becomes more difficult to sustain.
The Hidden Cost of Operational Friction
Customer Service is often where operational pressure becomes visible. It is rarely where it begins.
The customer contacts your business because something else has already failed. Perhaps:
- Marketing has created expectations the operation cannot fulfil.
- Product information isn’t clear enough.
- Inventory visibility is inaccurate.
- Delivery updates aren’t proactive.
- Teams are working from different information.
- Ownership becomes unclear between departments.
- Customers repeat themselves across multiple channels.
Every one of these creates unnecessary customer effort. Every one also carries a commercial cost: lost conversion, higher acquisition costs, lower customer lifetime value, increasing operational expense and declining trust.
The real question isn’t: “How quickly can we answer the contact?”
It’s: “Why did the customer need to contact us in the first place?”
Stop Measuring Symptoms
Many organisations are still measuring the visible outputs: contact volumes, response times, Customer Satisfaction and service levels.
These are important, but they are largely lagging indicators. They tell us what has already happened. They rarely explain why.
The world’s leading customer-centric organisations spend just as much time measuring operational friction. They ask:
- Which customer contacts should never happen?
- Where are we creating unnecessary effort?
- Which processes generate repeat demand?
- Which customer journeys destroy trust?
- What operational constraint is limiting growth?
Understanding these questions transforms Customer Service from a cost centre into a source of commercial insight.
Don’t Automate an Unclear Operation
Artificial Intelligence will undoubtedly reshape ecommerce operations. But AI should never become the starting point.
Automating inconsistent processes simply creates inconsistent experiences faster. Technology works best when it removes friction from an already well-designed operating model.
The greatest opportunities often exist behind the scenes:
- Intelligent routing
- Workflow automation
- Knowledge management
- Agent Assist
- Quality monitoring
- Root cause identification
- Operational analytics
Only once these foundations exist should businesses accelerate customer-facing automation.
The objective should never be maximum automation.
It should be maximum customer value with minimum customer effort.
Customer Operations Is Becoming a Competitive Advantage
For years, organisations have invested heavily in marketing, digital experience, commerce platforms and personalisation.
Yet many continue to operate customer journeys that remain fragmented behind the scenes.
The organisations creating sustainable competitive advantage are no longer asking: “Should we buy another technology platform?”
They’re asking: “How do we redesign Customer Operations so growth becomes easier, not harder?”
That requires looking across the entire operating model:
People. Process. Technology. Data. Automation. Governance. Leadership. Customer insight.
The answer is rarely one of these.
It is almost always the combination.
Five Questions Every Leadership Team Should Ask
Before investing in more people… Before implementing another AI solution… Before outsourcing… Ask yourselves:
1. Which customer contacts should never happen?
2. Where is operational friction quietly destroying profit?
3. Which customer journeys create unnecessary effort?
4. Where can AI genuinely improve the experience rather than simply reduce cost?
5. Could our operating model comfortably absorb another 50% growth?
If the answer to any of these is uncertain, the opportunity probably lies in redesigning the operating model before adding more technology or resource.
Join Our Executive Webinar
In this executive discussion, Martin Newman, international customer experience expert, board advisor and author of ROI Reimagined, joins Customer Contact Panel to explore why many ecommerce businesses mistake operational symptoms for operational causes.
Building on the themes explored in this article, Martin will examine how leading organisations are redesigning Customer Operations to improve customer experience while simultaneously reducing operational complexity and creating capacity for profitable growth.
During the webinar, we’ll explore:
- Why Customer Operations has become one of the biggest commercial differentiators in ecommerce
- How to identify the hidden operational friction limiting profitable growth
- Practical examples of organisations that have redesigned customer journeys rather than simply adding more people
- Where AI creates genuine customer value, and where it doesn’t
- How to build an operating model capable of scaling without increasing customer effort or cost-to-serve
Final Thought
Customer experience is no longer won by the organisation with the biggest marketing budget. Nor by the organisation with the most sophisticated technology. It is won by the organisation whose Customer Operations make it consistently easier for customers to buy, stay, and recommend. The businesses that will lead the next decade of ecommerce won’t simply generate more demand. They’ll be the ones best equipped to absorb it.
The subscription economy has become the preferred commercial model in the digital era. From its early pre-digital beginnings supported by Standing Orders and Direct Debits, the acceleration in adoption happened because three powerful trends converged:
- The digitisation of products and services
- The ability to store payments credentials securely
- The recognition within the investment community that recurring revenue is far more valuable than transaction revenue
Today, regulators, card schemes, banks and consumer protection agencies are introducing controls designed to place consumers firmly in control of the recurring payments underpinning the global subscription economy. Although regulatory approaches differ the UK, European Union and North America are all moving towards a common objective:
Consumers should retain effective control over recurring payments throughout the entire subscription lifecycle.
This principle is driving reforms relating to transparency, consent, authentication, renewal notices, cancellation journeys and dispute rights.
So how should organisations react? What does a reasonable response look like to respond to change and maintain revenue flows whilst reducing cost and risk?
To answer that, let’s look at what is driving change globally. Perhaps the most significant changes have come not from regulators but from the card brands themselves. The distinction between Customer Initiated Transactions (CITs) and Merchant Initiated Transactions (MITs) sits at the centre of modern subscription governance. A CIT occurs when a customer actively authorises a transaction. The initial subscription purchase normally falls into this category. An MIT occurs when the merchant subsequently charges the customer using previously obtained authority. Subscription renewals, annual renewals and usage-based billing are common examples.
Card schemes increasingly require merchants to demonstrate a clear link between the original CIT and subsequent MITs. In addition, Visa and Mastercard Stored Credential Frameworks require merchants to identify and categorise recurring transactions, maintain evidence of consent and provide stronger consumer disclosures.
As well as demanding more from their merchants, the card schemes are making it easier for consumers to request a ‘chargeback’. Historically subscription disputes were resolved between merchants and consumers. Increasingly consumers bypass merchants entirely and seek refunds through their card issuer. Issuers now possess more transaction data, improved recurring payment visibility and stronger dispute rights. Less control for merchants brings more and higher costs.
When we look specifically at geographical markets the UK has emerged as one of the most active subscription regulation markets. The Digital Markets, Competition and Consumers Act introduces enhanced consumer protections including reminder notices, cooling-off rights and simplified cancellation mechanisms. In addition, The Competition and Markets Authority has also signaled increasing scrutiny of subscription retention practices. The UK is additionally positioned to become a leading market for Open Banking Variable Recurring Payments which may begin to challenge card-based subscription models, even without any chargeback mechanism being in place to protect the consumer.
Irrespective of the markets organisations (merchants) operate in, those that are going to thrive in this new pressurised environment will have three things in common:
- Firstly, a customer engagement platform capable of analyzing customer interactions across all engagement activity, irrespective of customer engagement channel, across all business outcomes, right through to full payment history. Which means having the ability to view and analyze data across historical data silo’s to identify and deliver targeted conversations with customers and prospects capable of delivering desired outcomes
- Second, a payments capability that is absolutely focused on delivering more customer payments, more easily and at less cost. Which means leveraging a new generation of payment gateway functionality capable of orchestrating payments across multiple merchant acquirers in real time to uplift payments acceptance rates and reduce transaction costs. It also means (for those trading in the UK) adjusting to card scheme mandates for no PAN on cards beyond 2030 and migrating stored payment credentials to card scheme network based tokenisation.
- And finally, a broad and robust data governance capability embracing consumer rights and protections, regulatory compliance, third party oversight and merchant acquirer contractual obligations (PCI DSS compliance).
Recurring revenue remains attractive. Consumer convenience remains attractive. However, what we are likely to see in the next 12 to 36 months is greater cost and risk pressure on established workflows and business process supporting the subscription model.
Recurring revenue and convenience that cannot withstand regulatory scrutiny, issuer challenge or consumer dispute is increasingly becoming recurring risk.
For much of the last decade, customer experience investment was driven by a relatively simple argument. Better experiences create better outcomes. Today, that argument is no longer enough.
Customer Contact Panel sponsored research by Ryan Strategic Advisory through the 2026 CX Technology and Global Services Survey to explore a challenge we encounter regularly: what gives organisations the confidence to approve investment in customer operations transformation? We asked 815 enterprise executives what forms of external support would help them make faster and more confident decisions regarding contact centre technology, outsourcing and operational change.
The answer was remarkably clear. Proof. Business case and ROI modelling ranked as the single most important factor. Independent views on technology options, trade-offs and proven outcomes ranked immediately behind. Delivery model design also emerged as a major consideration.
Taken together, the findings reveal a significant shift in how organisations evaluate CX investments. Decision makers are no longer looking for promises. They are looking for evidence.
This reflects the environment many organisations now operate within. Budgets remain under pressure. Technology options continue to multiply. AI vendors are making increasingly ambitious claims. Outsourcing models are evolving. The number of potential solutions available to contact centre leaders has never been greater.
Ironically, more choice has made decision making harder. The challenge facing many organisations is not a shortage of opportunities. It is a shortage of confidence.
Can the supplier deliver? Will the technology work? How long will implementation take? What risks need to be managed? Most importantly, what return will the organisation receive in exchange for its investment?
The survey suggests that organisations increasingly want independent validation before committing to major decisions. This explains why advisory support, benchmarking, decision validation and technology assessment all scored strongly among respondents.
Executives are seeking reassurance that the choices they make are grounded in proven outcomes rather than marketing claims.
This has important implications for suppliers and internal transformation teams alike. Features are no longer enough. Capabilities are no longer enough. Even successful case studies may not be enough.
Organisations want to understand how a proposed solution will perform in their environment, against their objectives and within their commercial constraints.
That requires a different conversation. One focused less on products and more on outcomes. Less on innovation and more on implementation. Less on possibility and more on proof.
Perhaps the most significant finding from the survey is that decision making itself is becoming a competitive advantage. The organisations moving fastest are not necessarily those with the largest budgets or the newest technology.
They are the organisations that can build confidence, align stakeholders and create a credible business case for change.
In a market full of options, confidence may be the most valuable asset of all. And confidence starts with proving the ROI.
Catch up on the series by reading Why CFOs Hold the Key to CX Transformation here, followed by Who Really Drives CX Change? here.
Most customer experience transformation programmes begin with an assumption.
If the business wants to improve customer outcomes, the people responsible for customer experience will naturally drive change.
The reality appears more complicated.
As part of the 2026 CX Technology and Global Services Survey by Ryan Strategic Advisory, Customer Contact Panel sponsored research into a question we regularly encounter when supporting customer operations transformation programmes: who actually drives change inside large organisations? The results highlight a clear distinction between the executives who champion transformation and those who are more likely to support it once a direction has already been agreed.
When asked which board-level stakeholders are most likely to drive customer operations transformation, respondents consistently pointed towards CEOs, Managing Directors, Chief Operating Officers and Chief Customer Officers.
In fact, nearly seven in ten respondents identified CEOs as either enablers or strong enablers of change.
The Chief Customer Officer and Chief Marketing Officer scored even higher when it came to strong enabling influence.
These findings reinforce an important truth.
Successful CX transformation is rarely a technology initiative. It is usually a business initiative.
The strongest advocates for change tend to be leaders who are accountable for growth, competitiveness, customer retention or operational performance.
However, some of the survey’s most interesting findings relate to the roles that were notably absent from the list of major change drivers.
Chief People Officers and HR leaders were among the least likely to be identified as strong enablers.
Transformation Directors and Solutions Leaders performed better, but not as strongly as many might expect given that transformation is often their primary responsibility.
Even Chief Technology Officers were more likely to be viewed as enablers than strong enablers.
Why does this matter?
Because many organisations continue to position transformation projects around technology implementation rather than business outcomes.
Technology teams help make change possible.
Transformation teams help coordinate delivery.
But the survey suggests that the initial momentum often comes from commercial and operational leadership.
The leaders driving change are those closest to customer outcomes, growth targets and operational performance metrics.
For CX leaders seeking support for a new initiative, there is an important lesson.
The first challenge is not selecting the right solution.
The first challenge is building the right coalition.
Understanding who naturally supports change, who remains neutral and who may resist investment can dramatically improve the chances of success.
Many transformation programmes fail before they begin because they focus on technology selection before stakeholder alignment.
The data suggests the reverse approach may be more effective.
Get the right people around the table first.
Then decide what to do next.
If you missed the first article, Why CFOs Hold the Key to CX Transformation , you can read it here. Then continue to the third article, Show Me the ROI: What CX Leaders Need to Prove, here.
For years, the customer experience industry has focused on technology.
CRM, AI, automation, analytics, cloud migration and workforce optimisation have dominated conference agendas and boardroom discussions. Yet despite the growing number of available solutions, many organisations still struggle to move forward with meaningful change.
New research from the 2026 CX Technology and Global Services Survey suggests the problem may not be technology at all.
Customer Contact Panel sponsored a series of questions within the survey by Ryan Strategic Advisory, gathering the views of 815 enterprise executives responsible for strategic contact centre decisions across North America, Europe and Asia-Pacific. The findings reveal a striking pattern.
When respondents were asked which board-level stakeholders are most likely to drive or block change in contact centre operations, one role stood out above all others.
The CFO.
Forty percent of respondents identified the CFO or Finance Director as either a blocker or extreme blocker to customer experience investment decisions. No other executive role attracted a higher level of resistance. Meanwhile, only 36% viewed finance leaders as enablers or strong enablers.
That creates a significant challenge for anyone attempting to introduce new technology, redesign an operating model, or secure investment in customer service transformation.
The findings are not necessarily a criticism of finance leaders. In many organisations, the CFO is fulfilling exactly the role they are expected to play.
Their responsibility is not to champion innovation. Their responsibility is to protect capital allocation and ensure investments generate measurable returns.
The issue is that many CX initiatives are still presented in terms that finance teams struggle to validate.
Better experiences.
Improved customer journeys.
Reduced effort.
Greater engagement.
All worthwhile objectives, but often difficult to translate into financial outcomes.
The survey’s second question helps explain why this matters.
Respondents were asked what external support would help them make faster, more confident decisions around contact centre investment. The clear winner was business case and ROI modelling.
More than four out of five respondents rated ROI modelling as having either high or critical impact on decision making.
The message is straightforward.
Most CX leaders spend time trying to convince stakeholders that change is necessary. The data suggests they should spend more time proving that change is financially justified.
The organisations making progress are not necessarily those with the best technology.
They are the organisations that can clearly demonstrate the commercial impact of change.
If finance is holding the purse strings, then finance needs evidence.
The future of CX transformation may depend less on the quality of the solution and more on the quality of the business case behind it.
Continue the series by reading Who Really Drives CX Change? here, followed by Show Me the ROI: What CX Leaders Need to Prove here.
Guardrails amidst the chaos
The world of AI – perhaps especially in the contact centre and customer experience space – is clouded with exaggerated claims, disputed evidence and unqualified ‘experts’. Everyone talks about guardrails, but there’s no settled agreement as to what is and isn’t reasonable or acceptable. So legal regulations and requirements would presumably be helpful in defining some foundational guardrails? But at a federal level the US government is active opposed to any AI-specific regulation and in the UK, while the government points to its ‘sector led’ approach, there are no plans for an overarching AI law.
However, it’s very different in the EU where the AI Act has been law since 2024 and will be fully implemented from this August. The Act is often described as “the world’s first comprehensive AI legislation”.
In which case, if you’re based in the UK, North America, Africa or Asia you may well be thinking “why should I care? That doesn’t affect me”.
If so, you’d be wrong; very wrong.
Why the EU AI act matters to you
No EU presence? It doesn’t matter. If you have EU customers you will need to comply with the Act’s requirements. And even if you don’t your EU suppliers will. And even if you don’t have EU suppliers or partners, it’s quite likely that in the global regulatory vacuum the EU AI Act will become a default standard, similarly to the way GDPR did for data protection.
While the odds of your organisation being prosecuted under the Act are low, bear in mind that fines are at GDPR levels. So, for the gravest transgressions you’d be looking at €35 million or 7% of global annual turnover.
What does the Act say?
Unsurprisingly, the Act’s quite lengthy, but there are some key highlights to get your head around:
The definition of AI:
”a machine-based system designed to operate with varying levels of autonomy, capable of adapting after deployment, and generating outputs such as predictions, recommendations, content, or decisions that can influence physical or virtual environments”
What’s ok and what’s not:
- Unacceptable Risk AI: Banned totally
- Social scoring, manipulative AI, and biometric categorisation based on sensitive traits are prohibited
⚠ Watch Out
Use of black-box AI for things like fraud prevention or dynamic pricing could put you at risk.
- High-Risk AI: Strict new controls in place
- Applies to recruitment, education, healthcare, credit scoring, policing, and safety-critical infrastructure
Requirements: Detailed risk assessments, transparency, human oversight, and conformity checks before launch
⚠ Watch Out
Don’t assume you’re exempt. Even seemingly innocuous recruitment screening tools could fall within the scope of these rules.
- General-Purpose & Generative AI: New obligations
- Foundation models (like ChatGPT or image generators) must ensure transparency, appropriate labelling AI-generated content, management of systemic risks, and clarification of the use of copyrighted data
- Limited-Risk AI: Transparency required
- Chatbots and similar tools must clearly inform users they’re interacting with AI
⚠ Watch out! Many voice bot providers currently advise clients to hide the fact that customers are interacting with machines. This will need to change – even as it becomes increasingly hard for customers to tell.
- Minimal-Risk AI: Largely unaffected by the Act
- Spam filters, video game AI, and similar tools are mostly out of scope of the Act
Who carries the liability?
As you might expect, the Act differentiates between AI developers (providers) and AI users (deployers).
- Developers (providers) are liable for ensuring that AI systems comply with the Act’s requirements, including safety, transparency, traceability, and respect for fundamental rights. They are specifically liable if harm results from software defects, cybersecurity vulnerabilities, or algorithmic discrimination.
- Users (deployers) are responsible for the legal operation of AI under their control. They need to ensure proper monitoring, human oversight, and adherence to transparency obligations are in place. Users will be held liable if harm occurs due to misuse, failure to supervise, or neglecting operational safeguards.
This means there is less scope for commercial partners to attempt to contractually ‘offload’ legal obligations onto their customers or suppliers than we often see in the realm of data protection. Added to which, when so many organisation and service providers are taking the opportunities to adapt and build upon AI foundation models, they may find themselves legally regarded more as developers than users.
What’s to be done?
What’s clear is that the use of AI in customer experience and contact centres in alignment with the EU AI Act isn’t a one-team or one-time task. Organisations need to truly understand where AI is being used, to achieve what and how. This isn’t just a job for the compliance team. Tech, data, proposition, digital, risk, pricing, finance, legal and customer experience colleagues all need to be involved. And to stay involved as AI solutions innately change and develop over time.
It’s a classic cross-functional business change project, but one that is likely to spur or reflect significant changes in business rules and structures – as well as needing to become embedded into ‘business as usual’ processes.
Need Help Navigating the EU AI Act?
At Customer Contact Panel, we help organisations find and successfully implement compliant, effective AI solutions, so you can innovate with confidence and accountability.
Drop us a line and we’d be happy to have a chat.
If you’re looking for a practical breakdown of what the EU AI Act requires and how to prepare, read our detailed guide:
EU AI Act Compliance: What Every Business Needs to Know and Do
This Location Watch was prepared with insights from Lee Cahalane of SupportNinja and Dr. Louis Siebrits of Resolv Global alongside broader industry research and market data on Colombia’s BPO and CX landscape. These perspectives highlight why Colombia is increasingly recognised as a leading destination for North American and European markets, and how its outsourcing ecosystem continues to evolve in both scale and sophistication.
Colombia CX and BPO Outlook – 2026
Colombia has firmly established itself as a high-performing outsourcing destination, combining bilingual talent, cultural alignment, and a rapidly maturing CX ecosystem. Once viewed primarily as a cost-saving alternative, Colombia is now recognised as a strategic delivery hub offering both scale and sophistication. The country has also remained relatively insulated from broader regional geopolitical tensions and is steadily overcoming outdated perceptions of political and social instability.
The country’s growth is underpinned by strong export performance, a large and skilled workforce, and increasing global confidence in its outsourcing sector. With BPO contributing significantly to employment and economic output, Colombia continues to attract investment while expanding into higher-value services.
Talent, Language and Service Culture
One of Colombia’s most distinctive advantages is its bilingual workforce, particularly in English, Spanish, and Portuguese. Beyond fluency, Colombian Spanish is widely regarded as neutral and clear, making it ideal for pan-regional support across the US Hispanic market and Latin America.
Agents are often trained in global communication standards, enabling more natural and empathetic interactions that go beyond scripted responses. This service-first mindset is a key differentiator, especially as organisations seek to balance automation with human experience.
However, competition for highly proficient English speakers is increasing, making talent retention and development an important consideration for employers.
Strategic Location and Market Alignment
Colombia’s geographic position offers strong alignment with North American operations, with overlapping time zones enabling real-time collaboration and support. This removes many of the operational challenges associated with traditional offshore models.
For European organisations, Colombia also plays a valuable role as an extension of service coverage. It enables high-quality English and Spanish support into afternoon and evening hours, effectively supporting follow-the-sun models while maintaining operational control and service consistency.
Infrastructure, Scalability and Delivery Capability
Major cities such as Bogotá, Medellín, and Barranquilla provide modern infrastructure, strong connectivity, and secure operating environments aligned with international standards. These urban centres are supported by a broader network of emerging tier-two cities, helping providers scale efficiently while managing costs.
Local governments in these regions are also actively supporting the growth of the BPO sector through initiatives such as “English for Work” programmes and targeted tax incentives.
Colombia’s large population — the third largest in Latin America — further supports workforce scalability. This enables organisations to expand operations or adjust capacity in line with demand, an increasingly important requirement in today’s dynamic CX landscape.
Cost Efficiency and Operational Stability
Colombia remains cost-competitive compared to North America while offering greater operational stability than some traditional offshore markets. Lower wage structures are balanced by relatively healthy retention rates, supporting continuity and service quality.
This combination of cost efficiency and workforce stability makes Colombia particularly attractive for long-term CX programmes rather than short-term labour arbitrage.
Technology and Evolving Service Models
The Colombian BPO sector is actively embracing advanced technologies, including AI-assisted workflows, CRM platforms, and omnichannel support capabilities. Providers are increasingly equipped to manage voice, chat, email, and social interactions within integrated delivery models.
At the same time, the market is evolving beyond traditional BPO into Knowledge Process Outsourcing (KPO). Services now extend into areas such as technical support, digital marketing, finance, legal process outsourcing, software development, and R&D — reflecting a broader shift toward higher-value, knowledge-driven work.
Sector Coverage and Investment Momentum
Colombia supports a wide range of industries, including fintech, healthcare, retail, and technology. Its combination of sector expertise and scalable delivery models makes it suitable for both specialised and high-volume operations.
Global brands have increasingly chosen Colombia as a delivery hub. For example, Amazon and HubSpot operate significant technology and e-commerce teams in Bogotá, while retail brands such as Starbucks, Victoria’s Secret, Gap, Forever 21, Lacoste, and Versace utilise the country for customer support operations. Hospitality provider Marriott International and financial institutions including Bank of America and J.P. Morgan also maintain local operations supporting both back-office and technical functions.
In addition, tech and digital-first companies including AngelList, Modern Health, and Hired are leveraging Colombia for nearshore engineering and product teams. This trend highlights the country’s transition from a cost-focused BPO destination to a strategic hub for premium bilingual talent, particularly in Bogotá and Medellín.
What Clients Should Consider
While Colombia offers a compelling value proposition, there are several factors organisations should evaluate:
- Language quality can vary between providers, making thorough vetting essential
- Long-term success depends on strong operational alignment and governance
- Pricing models are evolving, with increasing adoption of outcome-based structures and AI-enabled efficiencies
- Talent competition, particularly for bilingual roles, may influence future hiring strategies
Bottom Line
Colombia has evolved into a powerhouse for CX and BPO. Its combination of linguistic strength, cultural alignment, scalable talent, and growing technical capability positions it as far more than a cost-saving option.
For organisations seeking resilient, high-quality, and scalable customer experience delivery, Colombia offers a well-balanced and future-ready solution. As global CX strategies continue to prioritise responsiveness, continuity, and value, Colombia’s role within outsourcing portfolios is set to expand further.
AI has amplified all of this. What was already a complex technology landscape is now louder, faster, more confident in its promises and far less easy to rationally assess.
The result is a familiar pattern. Reams of content. Lots of conversations. Plenty of demos. Very few decisions.
“The problem isn’t a lack of technology. It’s a lack of confidence about where to start.”
Too much choice, not enough direction
Most contact centre leaders are exposed to hundreds of tools, platforms and propositions. CCaaS, Automation, AI, Analytics, Workforce optimisation, Knowledge, Quality, Speech, Sentiment, and/or Real-time coaching.
Each promises transformation, yet few explain sequencing or iterative value.
Technology discussions often jump straight to an end state. Fully automated journeys. AI-first contact centres. Single platforms doing everything. The reality is that most organisations are not starting from a clean slate. They are operating with legacy systems, ingrained processes and teams who are already stretched.
When leaders are presented with change at scale, hesitation is a rational response.
“Indecision is rarely caused by resistance to change. It’s caused by unclear risk.”
One ecosystem, many perspectives
One of the most common mistakes we see is treating contact centre technology as a single audience decision. In reality, it is experienced very differently depending on where you sit.
Customers experience outcomes – Resolution, speed, effort.
Agents experience tools – Screens, prompts, workflows, knowledge.
Team Leaders experience data – Performance metrics, quality scores, coaching demands.
Executives experience cost, compliance, risk and return.
Technology fails when these perspectives are treated in isolation. A tool that improves reporting but makes life harder for agents will not deliver sustainable value. Automation that reduces contacts, but damages trust will quickly be rolled back.
“Technology only works when data flows through the organisation, not when it stops at functional boundaries.”
Why replacing everything may not always work
There is a temptation to believe that the answer is replacement. New platform. New vendor. Clean start.
Sometimes that is necessary. Often it is not. Make sure you have clarity as to what you need to achieve and the capability of the solution you are looking at as large-scale CCaaS or platform replacement is expensive, disruptive and can be slow. It introduces delivery risk at exactly the moment many organisations are under pressure to stabilise performance. It also assumes that the underlying processes are already fit for automation, which is rarely the case.
Some organisations have truly exhausted their tech ecosystem’s capabilities and potential.
But many organisations do not need everything at once, they need progress.
That is why we increasingly see value created through targeted, point-solution adoption. Technology that does one job well and (crucially) integrates into the existing environment.
“Momentum is more valuable than perfection.”
Starting where impact is visible
One of the most effective starting points we see for technology change is quality management.
Historically, quality assurance has been constrained by sampling. A handful of interactions reviewed each month, representing a fraction of actual customer conversations. Coaching is based on partial insight. Risk is often identified after the event.
Automation changes that dynamic. Moving from fractional sampling to full visibility unlocks far more than compliance. It enables better coaching, faster identification of issues, clearer insight into customer sentiment and more consistent experiences.
Importantly, this type of AI does not remove people from the process. It supports them.
- Agents receive clearer feedback.
- Team leaders focus on coaching rather than administration.
- Leaders gain confidence in what is happening across the operation
“AI delivers value fastest when it helps people do their jobs better, not when it tries to replace them.”
What good looks like now
The most effective contact centre leaders we work with are not chasing the biggest transformation story.
They are making deliberate choices.
They prioritise problems before platforms.
They sequence change rather than attempting to do everything at once.
They invest in technology that supports people and process, not just cost reduction.
They accept that doing nothing is still a decision, and often the riskiest one.
Technology will continue to evolve. AI will become more capable. Customer expectations will continue to rise. The organisations that succeed will be those that move with intent rather than waiting for certainty.
“The most effective contact centres are not the most automated. They are the most deliberate.”
The second half of 2025 saw a sharp acceleration in conversations about AI. While AI dominated the conversation at our roundtable, one theme cut through consistently: a growing disconnect between business ambition, technological momentum and the real needs of customers.
Boards are often pushing for rapid returns or exercising extreme caution. Technology vendors are promising transformation. Yet CX metrics still struggle to reward loyalty and long-term value, leaving CX leaders to reconcile competing pressures with limited levers.
Against this backdrop of uneven readiness for next-generation CX, we also heard clear examples of organisations making progress. Those succeeding are addressing these tensions through stronger governance, better-aligned metrics and more collaborative partner models.
This paper draws directly on those discussions to surface the CX challenges that matter most in 2026 and beyond, and to share practical experience on how to address them.
When AI holds up a mirror to CX
AI is revealing the true state of customer experience. Where journeys are well designed, data is connected and governance is clear, automation delivers value. Where those foundations are weak, AI simply scales existing problems faster.
Leaders shared examples of blanket automation strategies being rolled back, CX teams managing downstream fallout from decisions they did not own, and metrics that reward efficiency while quietly destroying long-term value. At the same time, we also heard from organisations getting it right, moving quickly but thoughtfully through clear ownership, outcome-based metrics and strong change management.
Why alignment now matters more than ever
As CX becomes increasingly hybrid, with human and AI blended across journeys, legacy thinking starts to break down. Traditional operational metrics struggle to explain value. Governance models lag behind technology. Cyber and data risks grow quietly in the background. And CX leaders are often held accountable without the authority to influence decisions upstream.
The organisations that will win in the next phase of CX are those that:
- Put strategy and use cases before technology
- Treat CX as a value multiplier, not just a cost centre
- Align boards, technology, CX and partners around shared outcomes
- Build solid data and security foundations before scaling AI
- Measure what truly matters to customers and the business
From fast adoption to sustainable advantage
This whitepaper explores the real decision gaps holding organisations back and offers practical guidance on how to close them. Drawing directly from practitioner insight, it covers governance, metrics, partner models, change management and cyber security, alongside seven practical steps CX leaders can take now.
Transformation is not optional. But speed alone is not success. The real inflection point is whether organisations can align people, metrics and leadership quickly enough to make AI work for customers and commercial outcomes alike.
The whitepaper is free to download and available below.
We would love to continue the conversation. Follow us on LinkedIn and share your experiences.